Advertiser Disclosure
This is an independent, advertising-supported comparison website. We may receive compensation from our partners when you click links on our site and take certain actions on their websites. This compensation helps keep this site free to use.
Compensation is one of several factors that may affect which products we feature, how prominently we feature them, and where they appear on our site, including, for example, their order on the page. Other factors may include our ratings and analysis, product availability, product features, and relevance to the page. We don't cover every credit card or offer available in the market. The order or prominence of products on our site does not necessarily reflect the rating we assign to a product or our assessment of its overall quality.
Compensation never affects our product ratings, analysis, or opinions, and our partners cannot pay us for a higher rating or a more favorable review.
Best Cash Back Credit Cards of 2026
 By CardAnalyst EditorsFact checkedUpdated September 30, 2026
The best cash back credit cards do something simple: give you money back on spending you were going to do anyway.
The trick is finding the card that pays you the most for the way you spend. A card with a great headline rewards rate isn’t very useful if most of your spending falls somewhere else.
We’ve evaluated 261 credit cards across 31 data points, with a ratings model built specifically for cash back cards.
The cards below are the ones we think offer the best combination of rewards, value, and ease of use.
Best Overall Credit Card
Chase Freedom Unlimited®
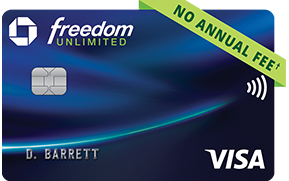
Pick this card if: You want one card that does nearly everything well, with strong rewards, a valuable welcome bonus, and a useful 0% intro APR period.
- Welcome Bonus
- $200
- Rewards Rate
- 1.5%-5% cash back
- Annual Fee
- $0
- Balance Transfer Intro APR
- 0% intro APR on balance transfers for 15 months
- Purchases Intro APR
- 0% intro APR on purchases for 15 months
- Regular APR
- 18.24%-27.74% Variable APR
- Recommended Credit Score
- 670-850 (Good to Excellent)
Card Details
- Earn a $200 Bonus after you spend $500 on purchases in your first 3 months from account opening
- Enjoy 5% cash back on travel purchased through Chase Travel℠, our premier rewards program that lets you redeem rewards for cash back, travel, gift cards and more; 3% cash back on drugstore purchases and dining at restaurants, including takeout and eligible delivery service, and 1.5% on all other purchases.
- No minimum to redeem for cash back. You can use points to redeem for cash through an account statement credit or an electronic deposit into an eligible Chase account located in the United States!
- Enjoy 0% Intro APR for 15 months from account opening on purchases and balance transfers, then a variable APR of 18.24% - 27.74%.
- No annual fee – You won't have to pay an annual fee for all the great features that come with your Freedom Unlimited® card
- Keep tabs on your credit health, Chase Credit Journey helps you monitor your credit with free access to your latest score, alerts, and more.
- Member FDIC
Pros & Cons
Pros
- Lucrative, easy-to-earn welcome bonus
- Above-average 0% intro APR period
- Solid unlimited cash back rate
Cons
- Other cards can earn more (but are often more complicated)
- Foreign transaction fee
Why we like it
There just aren’t many credit cards that are this good at this many things. You get strong rewards, a valuable welcome bonus, and a solid 0% intro APR period, all with no annual fee. It may not lead every individual category, but it's very good at pretty much everything. That’s why it’s our Best Overall Credit Card for 2026 and one of the most popular credit cards in America.
Opens in a new tab: Apply now for the Chase Freedom Unlimited® →Best for huge cash back potential
Discover it® Cash Back
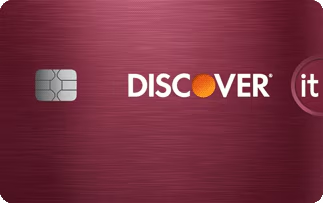
Pick this card if: You want a high-upside card with big welcome bonus and rewards potential, plus a strong 0% intro APR offer.
- Welcome Bonus
- Discover will match all the cash back you’ve earned at the end of your first year.
- Rewards Rate
- 1%-5% Cash Back
- Annual Fee
- $0
- Balance Transfer Intro APR
- 0% intro APR on balance transfers for 15 months
- Purchases Intro APR
- 0% intro APR on purchases for 15 months
- Regular APR
- 17.49%-26.49% Variable APR
- Recommended Credit Score
- 670-850 (Good to Excellent)
Card Details
- INTRO OFFER: Unlimited Cashback Match for all new cardmembers. Discover will automatically match all the cash back you’ve earned at the end of your first year! There’s no minimum spending or maximum rewards. You could turn $150 cash back into $300.
- Earn 5% cash back on everyday purchases at different places you shop each quarter like grocery stores, restaurants, gas stations, and more, up to the quarterly maximum when you activate. Plus, earn unlimited 1% cash back on all other purchases.
- Redeem cash back for any amount. No annual fee.
- 0% intro APR on purchases and balance transfers for 15 months; 17.49% - 26.49% variable APR after that; balance transfer fee applies.
- Terms and conditions apply.
Why we like it
This card offers the potential for high cash back returns, thanks to an innovative welcome bonus and rewards structure. Throw in a strong 0% intro APR offer and no annual fee, and it's easy to see why this is a popular pick for those looking to achieve serious cash back.
Opens in a new tab: Apply now for the Discover it® Cash Back →Best for flat rate cash back
Citi Double Cash® Card
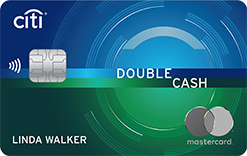
Pick this card if: You want one of the best flat cash back rates available, or an excellent balance transfer offer — or both.
- Welcome Bonus
- $200
- Rewards Rate
- Earn 2% cash back on every purchase
- Annual Fee
- $0
- Balance Transfer Intro APR
- 0% intro APR on balance transfers for 18 months
- Regular APR
- 18.24%-28.49% Variable APR
- Recommended Credit Score
- 670-850 (Good to Excellent)
Card Details
- Earn $200 cash back after you spend $1,500 on purchases in the first 6 months of account opening. This bonus offer will be fulfilled as 20,000 ThankYou® Points, which can be redeemed for $200 cash back.
- Earn 2% on every purchase with unlimited 1% cash back when you buy, plus an additional 1% as you pay for those purchases. To earn cash back, pay at least the minimum due on time. Plus, earn 5% total cash back on hotel, car rentals and attractions booked with Citi Travel.
- Balance Transfer Only Offer: 0% intro APR on Balance Transfers for 18 months. After that, the variable APR will be 18.24% - 28.49%, based on your creditworthiness.
- Balance Transfers do not earn cash back. Intro APR does not apply to purchases.
- If you transfer a balance, interest will be charged on your purchases unless you pay your entire balance (including balance transfers) by the due date each month.
- There is an intro balance transfer fee of 3% of each transfer (minimum $5) completed within the first 4 months of account opening. After that, your fee will be 5% of each transfer (minimum $5).
Pros & Cons
Pros
- Fantastic unlimited flat cash back rate
- Long 0% intro APR balance transfer offer
- No annual fee
Cons
- No 0% intro APR offer for purchases
- Higher spend required to trigger welcome bonus than some competing cards
Why we like it
The flat rate cash back is one of the best available today (Earn 2% cash back on every purchase). This card pairs that with a well above-average balance transfer offer and a solid welcome bonus. It's a great option for those who value simplicity and high flat cash back earnings you don't have to think about, or a strong balance transfer offer, or both.
Opens in a new tab: Apply now for the Citi Double Cash® Card →Excellent unlimited flat cash back rate
Wells Fargo Active Cash® Card
Pick this card if: You want one of the strongest flat cash rewards rates available: unlimited 2% cash rewards on purchases.
on Wells Fargo's website
Rates & Fees for Wells Fargo Active Cash® Card (opens in a new tab)
- Welcome Bonus
- $100
- Rewards Rate
- Unlimited 2% cash rewards on purchases
- Annual Fee
- $0
- Balance Transfer Intro APR
- 0% intro APR for 12 months from account opening on qualifying balance transfers
- Purchases Intro APR
- 0% intro APR for 12 months from account opening on purchases
- Regular APR
- 18.74%, 24.74%, or 28.74% Variable APR
- Recommended Credit Score
- 670-850 (Good to Excellent)
Card Details
- Apply Now to take advantage of this offer and learn more about product features, terms and conditions.
- Earn a $100 cash rewards bonus after spending $500 in purchases in the first 3 months.
- Earn unlimited 2% cash rewards on purchases.
- 0% intro APR for 12 months from account opening on purchases and qualifying balance transfers. 18.74%, 24.74%, or 28.74% variable APR thereafter; balance transfers made within 120 days qualify for the intro rate and fee of 3% then a BT fee of up to 5%, min: $5.
- $0 annual fee.
- No categories to track or remember and cash rewards don’t expire as long as your account remains open.
- Find tickets to top sports and entertainment events, book travel, make dinner reservations and more with your complimentary 24/7 Visa Signature® Concierge.
- Up to $600 of cell phone protection against damage or theft. Subject to a $25 deductible.
Pros & Cons
Pros
- Exceptional unlimited flat cash rewards rate
- $0 annual fee
Cons
- Other cards offer longer 0% intro APR period
- Other cards offer larger welcome bonus
Why we like it
It doesn’t get much better than unlimited 2% cash rewards if you want a simple card you can use for most of your spending. There are no bonus categories to track, and the card also gives you a welcome bonus and a 0% intro APR offer, all with no annual fee. It’s an excellent choice if you want strong rewards without having to think much about how you earn them.
Opens in a new tab: Apply now for the Wells Fargo Active Cash® Card →Blue Cash Preferred® Card from American Express
Pick this card if: You want a top rewards rate on things like groceries, streaming, and gas -- plus a potentially lucrative welcome bonus.
on American Express's website
Rates & Fees for Blue Cash Preferred® Card from American Express (opens in a new tab)
- Welcome Bonus
- As High as $300 cash back. Find Out Your Offer.
- Rewards Rate
- 1%-6% Cashback
- Annual Fee
- $0 intro annual fee for the first year, then $95
- Balance Transfer Intro APR
- 0% intro APR on balance transfers for 12 months from the date of account opening
- Purchases Intro APR
- 0% intro APR on purchases for 12 months from the date of account opening
- Regular APR
- 19.74%-28.74% Variable APR
- Recommended Credit Score
- 670-850 (Good to Excellent)
Card Details
- Apply and find out your welcome offer. As High As $300 cash back* after you spend $3,000 in purchases on your new Card within the first 6 months of Card Membership. Welcome offers vary and you may not be eligible for an offer. Apply, and if approved: 1. Find out your offer amount 2. Accept the Card with your offer 3. Spend $3,000 in 6 months 4. Receive the cash back. *Cash back is received in the form of Reward Dollars that can be redeemed for a statement credit or at Amazon.com checkout.
- $0 intro annual fee for the first year, then $95.
- Enjoy 0% intro APR on purchases and balance transfers for 12 months from the date of account opening. After that, your APR will be a variable APR of 19.74%-28.74%.
- Plan It®: Buy now, pay later with Plan It. Split purchases of $100 or more into equal monthly installments with a fixed fee so you don’t have the pressure of paying all at once. Simply select the purchase in your online account or the American Express® App to see your plan options. Plus, you’ll still earn rewards on purchases the way you usually do.
- Earn 6% cash back at U.S. supermarkets on up to $6,000 per year in eligible purchases (then 1%), 6% cash back on select U.S. streaming subscriptions, 3% cash back at eligible U.S. gas stations and on transit (including taxis/rideshare, parking, tolls, trains, buses and more) purchases and 1% cash back on other purchases. Cash Back is received in the form of Reward Dollars that can be redeemed as a statement credit and at Amazon.com checkout.
- Get up to a $10 monthly statement credit after using your enrolled Blue Cash Preferred® Card for a subscription purchase, including a bundle subscription purchase, at DisneyPlus.com, Hulu.com, or Stream.ESPN.com U.S. websites. Subject to auto-renewal.
- Terms Apply.
How to choose a cash back credit card
Start with your actual spending, not the rewards table.
Look at the last few months of purchases and ask where most of your money goes. Groceries? Restaurants? Gas? Online shopping? Or is your spending spread pretty evenly across everything?
That usually tells you what type of cash back card makes the most sense.
Here’s what we’d compare most closely:
- Rewards rate. Look at what the card earns on the purchases you make most often, not just its highest advertised rate.
- Flat-rate vs. category rewards. A flat-rate card pays the same rate on most purchases and takes almost no thought. Category cards can earn more, but only if their bonus categories line up with your spending.
- Spending caps. A high rewards rate can become much less impressive if it only applies to a limited amount of spending before dropping to a lower rate.
- Welcome bonus. A good bonus can add a lot of first-year value, especially if you can earn it through normal spending you were already planning.
- Annual fee. A fee can be worthwhile, but the additional rewards and benefits should comfortably make up for it.
- Redemption options. Cash back should be easy to use. Check how you can redeem it and whether the card requires a minimum amount before you can cash out.
- Foreign transaction fee. If you expect to use the card outside the U.S., check this before choosing. A foreign transaction fee can quickly outweigh the cash back you earn.
- Other useful features. A strong intro APR offer or other benefits can help break a close tie, but we wouldn’t let them distract from the rewards themselves.
A cash back card should fit your spending without requiring you to change it.
Flat-rate cash back vs. bonus categories
This is probably the biggest decision when choosing a cash back card.
A flat-rate cash back card gives you the same rewards rate on most purchases. You don’t have to remember which card to use at the grocery store or whether this quarter’s bonus category has been activated.
A category cash back card pays more in certain areas of spending. That can be more valuable if those categories happen to match where a lot of your money goes.
Neither approach is automatically better.
If your spending is spread across a lot of different things, a strong flat-rate card can be hard to beat. If a large share of your budget goes toward one or two categories, a card that rewards those purchases more heavily can come out ahead.
And if you enjoy optimizing, you don’t have to choose. You can use a category card where it earns more and a flat-rate card for everything else.
We wouldn’t build a complicated card setup for a few extra dollars a month unless you actually enjoy managing it.
Don’t get distracted by the highest rewards rate
A card advertising 5% or 6% cash back can look obviously better than one offering a lower rate.
Sometimes it is.
But the number by itself doesn’t tell you much. That higher rate may only apply to one category. There may be a spending cap. The category might rotate throughout the year. Or it simply might not be somewhere you spend much money.
Imagine you spend $100 a month in a card’s highest-earning category but $2,000 a month everywhere else. The rewards on that other $2,000 probably matter a lot more.
We care more about how much cash back a card is likely to earn across your actual spending than the biggest percentage on its marketing page.
Welcome bonuses can add a lot of first-year value
Cash back isn’t only about the ongoing rewards rate.
A strong welcome bonus can be worth several months, and sometimes much more, of normal rewards earning.
That matters most when you can qualify without changing your behavior.
If you already have a large planned expense coming up, for example, that spending may help you earn a welcome bonus while also generating the card’s normal cash back.
What we wouldn’t do is buy things you didn’t need just to hit a spending requirement. Earning a bonus doesn’t help if you had to spend unnecessary money to get it.
We also wouldn’t choose a weak long-term card solely because its opening bonus is larger. The bonus happens once. Your normal rewards rate is what you’ll live with afterward.
How much can cash back actually be worth?
Say you put $2,000 a month of normal spending on a card earning an average of 2% back.
That’s about $480 per year without changing what you buy.
Someone who spends more, or who does a good job matching higher rewards rates to their biggest spending categories, can earn considerably more.
That’s why relatively small differences between cards can matter over time. An extra half-percent on a purchase doesn’t feel like much at checkout, but repeated across tens of thousands of dollars in spending over several years, it adds up.
At the same time, getting every last fraction of a percentage point isn’t necessary. A card that’s easy to use and earns a strong rate consistently can be a better fit than one that requires constant attention.
Should you use one cash back card or several?
One can be plenty.
A good flat-rate card can cover nearly everything and requires almost no effort. For someone who doesn’t want to think about credit card rewards, that’s a strong setup.
Using two or three cards can increase your rewards if each one has a clear role.
Maybe one card earns more on your biggest spending category while another handles everything else. That’s still pretty easy to manage.
Beyond that, the extra rewards have to justify the extra complexity.
If you’re standing at the register trying to remember which of six cards earns an extra percentage point on this particular purchase, you may have gone further than you need to.
Are cash back cards with annual fees worth it?
They can be.
Most people have plenty of strong cash back options without annual fees, but a fee-based card can still make sense if your spending allows you to earn enough additional rewards to come out ahead.
Use your own spending rather than the card’s theoretical maximum value. If the math only works because you’re assigning full value to benefits you normally wouldn’t use, the card probably isn’t as valuable to you as it looks on paper.
Don’t let cash back cost you interest
Cash back works best when you pay your statement balance in full and avoid interest.
If you’re carrying a balance at a high APR, the interest can quickly outweigh the rewards you earn. In that situation, we’d usually focus on reducing the cost of the debt before trying to squeeze more cash back out of your spending.
Rewards should make purchases you were already going to make more valuable. They shouldn’t be the reason you borrow money.
Cash back vs. travel rewards
Cash back is generally the simpler choice. You usually know what your rewards are worth, and redeeming them doesn’t require much strategy.
Travel rewards can offer more upside for some people, particularly frequent travelers, but the value can depend more heavily on how you redeem them.
If you’d rather earn something predictable and use it however you want, cash back is hard to argue with. If travel is a big part of your life and you’re willing to put a little more thought into rewards, points or miles may offer more potential value.
Our guide to cash back vs. points goes deeper into that choice.
How we rate cash back credit cards
For cash back cards, the rewards come first.
We look at how much a card can realistically earn across different types of spending, not just its highest advertised rate. We also consider spending caps, annual fees, welcome bonuses, and how easy the rewards are to redeem.
A card that earns slightly more on paper isn’t necessarily better if getting that extra value requires a lot more work or only applies to a narrow slice of spending.
We also consider other useful features, including intro APR offers and cardholder benefits, but they’re secondary to how well the card actually earns cash back.
[See how we rate credit cards →]
Frequently asked questions about cash back credit cards
How do cash back credit cards work?
Cash back cards reward eligible purchases with a percentage of what you spend.
Depending on the card, you might earn the same rate on most purchases or higher rates in certain spending categories. Rewards can typically be redeemed in forms such as statement credits or cash, depending on the program.
What is a good cash back rate?
It depends on the type of card.
Flat-rate cards generally trade the highest possible rewards rate for simplicity, while category cards can pay more on specific types of purchases.
We’d judge a rewards rate by how much it earns across your actual spending rather than comparing the single highest number on each card.
Is 2% cash back good?
For a card that earns the same rate across most purchases, 2% cash back is a very strong rate.
A category card may earn considerably more on certain purchases, but a flat-rate card can make up ground by paying a solid rate on nearly everything.
Is a cash back card worth it if I don’t spend much?
It can be, particularly if there’s no annual fee.
Your rewards will naturally be smaller if your spending is lower, but you shouldn’t spend more just to make a cash back card feel worthwhile.
Should I get a flat-rate or category cash back card?
A flat-rate card tends to make more sense if you value simplicity or your spending is spread across many categories.
A category card can be better if a large share of your spending falls into areas where the card earns more.
If you’re comfortable using more than one card, combining the two approaches can work well.
Do cash back rewards expire?
It depends on the card.
Some rewards remain available as long as the account stays open and in good standing, while other programs have different rules. Closing an account can also cause you to lose unredeemed rewards in some programs, so check the terms and consider redeeming what you’ve earned before closing a card.
Do cash back cards have minimum redemption amounts?
Some do.
Depending on the program, you may need to accumulate a certain amount of cash back before you can redeem it. Other cards let you redeem almost any amount.
It’s not usually the most important factor, but it’s worth checking if you value flexibility.
Can you earn cash back while using a 0% intro APR?
Generally, yes, if the card normally earns rewards on eligible purchases.
That can make a cash back card with a strong 0% purchase offer especially useful for a large planned expense. Just make sure the promotional period gives you enough time to pay the balance off before interest begins.